


Most buyers in the UAE begin their property search with a price range in mind, but without knowing what a bank will actually lend them. Getting a home loan pre approval changes that: it gives you a confirmed borrowing limit from a lender before you view a single property, so your search is grounded in real numbers from the start.
This guide walks you through what home loan pre-approval is, the documents required for salaried and self-employed applicants, how to apply in a branch or online, how long the letter stays valid, and how it positions you more effectively when you are ready to buy a property.
- What is home loan pre-approval?
- Pre-qualification, pre-approval, and final approval: What’s the difference?
- Who can apply for mortgage pre-approval in the UAE?
- Documents you need to apply
- How to apply for pre-approval
- How long does pre-approval last?
- How pre-approval strengthens your offer
- Key takeaways
- FAQs
What is home loan pre-approval?
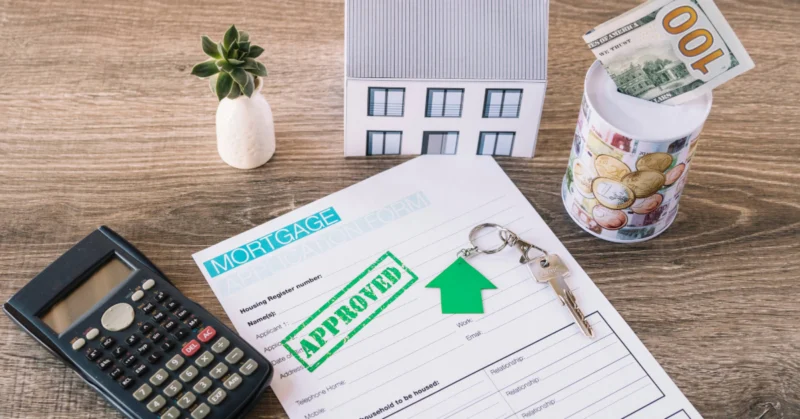
Home loan pre-approval is a formal assessment by a bank or lender of your financial profile. The bank reviews your income, employment, existing debts, and credit history through the Al Etihad Credit Bureau (AECB) to determine the maximum loan amount it would be willing to offer. You then get a written letter, the bank pre-approval home loan letter, confirming the indicative loan amount, an approximate interest rate, and a validity period.
A pre-approval letter is not a final mortgage offer. Final approval comes later, once you have identified a specific property, the bank has carried out an independent valuation, and legal title checks have been completed. Pre-approval is a conditional commitment: it confirms what the bank is prepared to lend in principle, subject to the property meeting its requirements.
Pre-qualification, pre-approval, and final approval: What’s the difference?
Mortgage pre-approval sits in the middle of a three-stage process. Understanding where each stage fits helps you plan your timeline and know what to expect.
| Stage | What the bank looks at | Reliability | Binding? | Typical turnaround |
| Pre-qualification | Your own stated income and liabilities | Estimate only | No | Same day |
| Pre-approval | Verified income, AECB credit check, employment, all liabilities | Conditional commitment | Conditional | 3–7 working days |
| Final approval | Pre-approved financials + property valuation and legal title checks | Firm offer | Yes, once signed | 2–4 weeks |
Who can apply for mortgage pre-approval in the UAE?

To be eligible for a mortgage pre approval in the UAE, most banks require applicants to meet these criteria:
- UAE resident (non-residents may be eligible under separate criteria, with higher deposit requirements)
- At least 21 years old
- No older than 65 at the point of loan maturity for salaried applicants; some banks extend this to 70 for self-employed applicants
- Stable and verifiable income, typically a minimum of AED 15,000 per month for salaried applicants (this varies by bank)
The Central Bank of the UAE caps total monthly debt repayments, including the new mortgage, at 50% of gross monthly income. This is the Debt Burden Ratio (DBR). Banks must also stress-test your repayment capacity at a rate 2 to 4 percentage points above the current rate, which may lower the maximum loan available to you.
The loan amount is also constrained by the loan-to-value (LTV) ratio. The Central Bank of the UAE sets the following maximum LTV limits.
| Borrower | Property type | Max LTV | Min deposit |
| UAE Nationals | First home, valued up to AED 5M | 85% | 15% |
| UAE Nationals | First home, valued over AED 5M | 75% | 25% |
| UAE Nationals | Second home / investment property | 65% | 35% |
| Expats | First home, valued up to AED 5M | 80% | 20% |
| Expats | First home, valued over AED 5M | 70% | 30% |
| Expats | Second home / investment property | 60% | 40% |
| All buyers | Off-plan purchase | 50% | 50% |
Individual banks may apply stricter limits than the Central Bank’s maximums. Down payments must come from your own funds. You cannot use a personal loan to cover the deposit.
Explore the Available Townhouses for Sale in Dubai
-
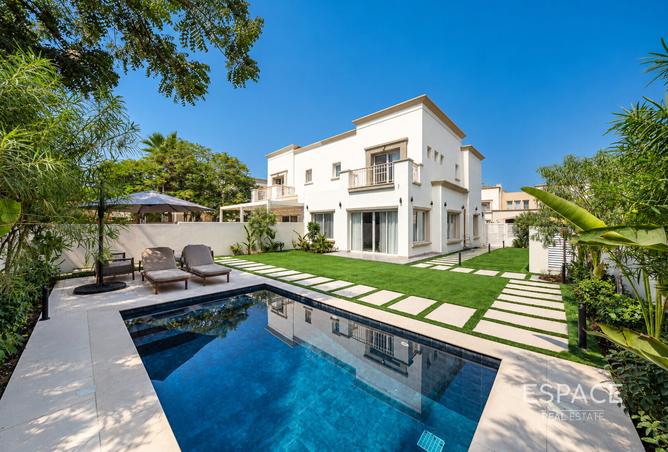

Townhouse
Listed 3 weeks ago
6,999,999 AED
4 Bed | Fully Extended | Turn Key | VOT
Springs 15, The Springs, Dubai
4
4
4,154 sqft
-
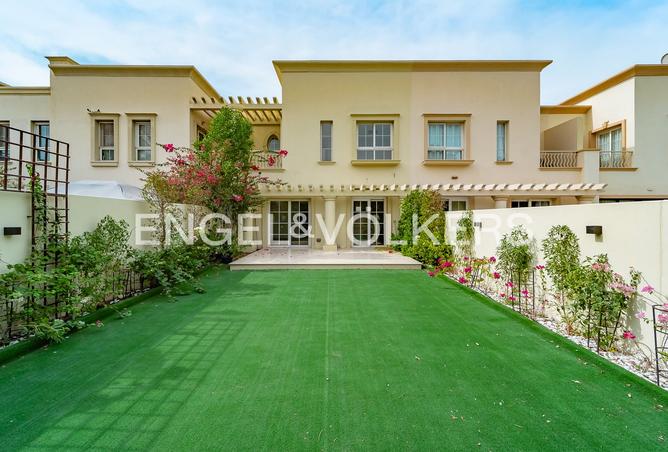
Townhouse
Listed 1 week ago
4,499,999 AED
Type 4M | Backing Park & Pool | Vacant
Springs 3, The Springs, Dubai
3
3
2,204 sqft
-
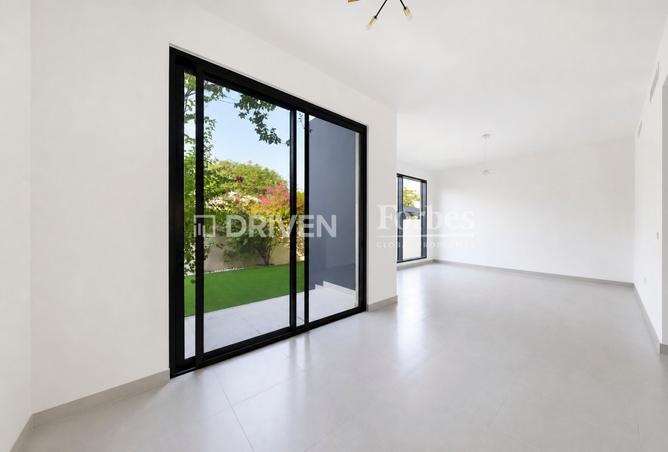
Townhouse
Listed 3 days ago
5,150,000 AED
Genuine Sale | Community Expert | Great Location
Maple 1, Maple, Dubai Hills Estate, Dubai
4
4
2,175 sqft
-

Townhouse
Listed 2 weeks ago
3,850,000 AED
End Unit - Single Row | Type A - Vacant Unit
Arabella Townhouses 2, Arabella Townhouses, Mudon, Dubai
3
4
3,093 sqft
-
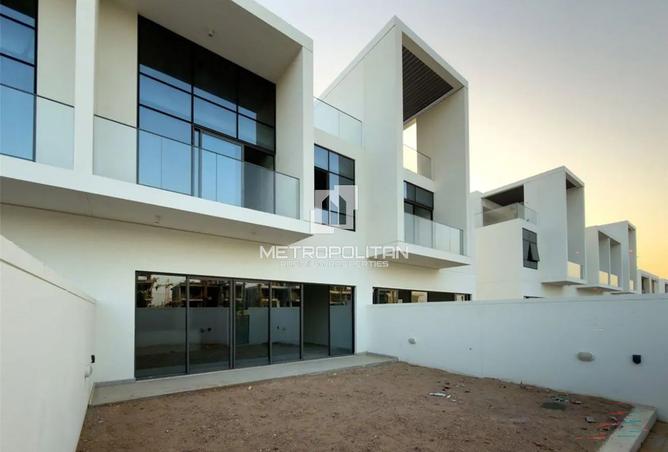
Townhouse
Listed 3 weeks ago
5,800,000 AED
Exclusive | Middle Unit | Vastu | Multiple Options
Opal Gardens, District 11, Mohammed Bin Rashid City, Dubai
4
5
2,836 sqft
-
Townhouse
Listed 1 day ago
9,094,777 AED
Spacious Home, Elevated Family Living, Corner Unit
Pinewood Estates Homes, Jumeirah Golf Estates, Dubai
4
5
5,307 sqft
-
Townhouse
Listed 1 day ago
9,094,777 AED
Corner End Unit, Big Plot, Ideal Family Home
Pinewood Estates Homes, Jumeirah Golf Estates, Dubai
4
5
5,307 sqft
-
Townhouse
Listed 1 day ago
7,177,777 AED
Mid Unit, Modern Family Home, Enquire Now
Pinewood Estates Homes, Jumeirah Golf Estates, Dubai
4
5
3,003 sqft
-
Townhouse
Listed 1 day ago
7,177,777 AED
All Ensuite Bedroom, G+1, Amazing Livable Area
Pinewood Estates Homes, Jumeirah Golf Estates, Dubai
4
5
3,003 sqft
-
Townhouse
Listed 1 day ago
3,400,000 AED
Prime Location | Handover Soon | Motivated Seller
Mudon Al Ranim 7, Mudon, Dubai
3
4
1,889 sqft



Documents you need to apply
Submitting a complete document pack is the fastest way to get a decision. Incomplete files are the most common reason applications take longer. The documents required differ for salaried and self-employed applicants.
| Document | Salaried | Self-employed |
| Passport copy | Required | Required |
| UAE residency visa | Required | Required |
| Emirates ID | Required | Required |
| Salary certificate or employment letter | Required | — |
| Payslips (last 3–6 months) | Required | — |
| Bank statements (last 6 months) | Required | Required |
| Trade licence | — | Required |
| Memorandum of Association (MOA) | — | Required |
| Audited financial statements (last 2 years) | — | Required |
| Disclosure of existing loans and liabilities | Required | Required |
Some banks may also ask you to provide your AECB credit report, which you can request directly through the Al Etihad Credit Bureau.
How to apply for pre-approval
You can apply for pre-approval directly with a bank or through a licensed mortgage broker. Using a broker has one practical advantage: a broker can submit to multiple lenders simultaneously, so you receive several offers to compare without making separate applications.
To get pre-approved for a home loan, follow these steps:
- Before approaching a bank, use a home loan pre approval calculator such as the Property Finder mortgage calculator to get an indicative borrowing range. It shows estimated monthly repayments based on purchase price, deposit, interest rate, and term.
- Choose your approach. Decide whether to apply directly with a bank or through a broker. A broker is especially useful if you are unsure which lender’s criteria you meet, or if you want to compare several offers at once.
- Gather your documents. Prepare your full document set before you submit. Submitting everything at once avoids back-and-forth and shortens processing time.
- Submit your application. You can apply in a branch or, with many lenders, get pre-approved for a home loan online through the bank’s digital portal. Home loan pre approval online applications follow the same review process as in-branch submissions.
- The bank reviews your file. The bank verifies your income and employment, checks your AECB credit history, and calculates your Debt Burden Ratio.
- Receive your pre-approval letter. Once approved, the bank issues a letter confirming the maximum loan, the indicative rate, and the validity period. Processing typically takes 3 to 7 working days for a complete file.
How long does pre-approval last?
Most bank pre-approval letters in the UAE are valid for 60 to 90 days, though some lenders issue shorter validity periods of 30 days. If you have not completed a purchase within that window, you will need to reapply with updated documents. The bank may recalculate the approved amount if your income, liabilities, or credit profile have changed since the original assessment.
Knowing when to get pre-approved for a home loan depends on how close you are to being ready to buy an apartment for sale in Dubai. If you are still exploring areas and comparing properties, it may be worth waiting until you are closer to committing, so your letter is still valid when you find the right property.
How pre-approval strengthens your offer
Sellers and their agents take pre-approved buyers seriously. A pre-approval letter signals that your finances have been verified by a bank, reducing the risk that the deal will fall apart at the financing stage. In a competitive situation, this can be the difference between securing a property and losing it to another buyer.
Pre-approval also accelerates the final mortgage process. Because the bank has already reviewed your financial profile, the final approval stage focuses on the property itself: valuation, legal title checks, and registration. This shortens the overall timeline between agreeing a price and completing the purchase.
Browse properties for sale in Dubai and across the UAE, and use the Property Finder mortgage calculator to run the numbers on any property you shortlist. Keeping your searches within your pre-approved range avoids the need to renegotiate financing at a later stage.
Key takeaways
- Securing home loan pre-approval before you search confirms your real borrowing limit and prevents time spent on properties outside your budget.
- The process involves a full financial assessment, including an AECB credit check and Debt Burden Ratio calculation. Submit a complete document pack to avoid delays.
- Pre-approval letters are typically valid for 60 to 90 days; begin your property search promptly and be prepared to reapply if the letter expires before you complete a purchase. Check the available villas for sale in Dubai on Property Finder.
- A pre-approval letter strengthens your offer: it tells sellers your financing is already in progress, reduces transaction risk, and allows final mortgage approval to move faster.
FAQs
For a complete document file, most banks process a home loan pre-approval in 3 to 7 working days. If documents are missing, the process takes longer. Working with a mortgage broker can help, as brokers know each bank’s requirements and can flag gaps before submission.
Most banks pull your AECB credit report as part of the pre-approval assessment. This is a hard inquiry, which may have a small temporary effect on your credit score. If you apply to multiple banks within a short window, credit bureaus typically count this as a single inquiry period, so it is better to compare and apply to several lenders at once rather than spacing applications out over months.
Many UAE banks now offer home loan pre approval online through their digital portals or mobile apps. The document requirements and review process are the same as for in-branch applications. Some lenders also allow applications through a mortgage broker’s platform, which can submit to multiple banks simultaneously.
Most banks require a minimum monthly salary of AED 15,000 for salaried applicants, though requirements vary by lender. Self-employed applicants need to demonstrate stable, verifiable income through audited financials and bank statements. The Central Bank of the UAE’s Debt Burden Ratio cap means your total monthly loan repayments, including the new mortgage, cannot exceed 50% of your gross monthly income.
Yes. Applying to more than one bank lets you compare loan amounts, rates, and terms. A mortgage broker can submit to multiple lenders on your behalf using a single document pack. Each application involves an AECB credit check, so it is worth comparing banks’ offers carefully before applying rather than applying broadly and then narrowing down.


